

Sensex Jumps 1,109 Points To 73,034, Nifty Tops 22,700 As IT Stocks Stage Stunning Comeback
October 13, 2026 | by NammaStockMarket
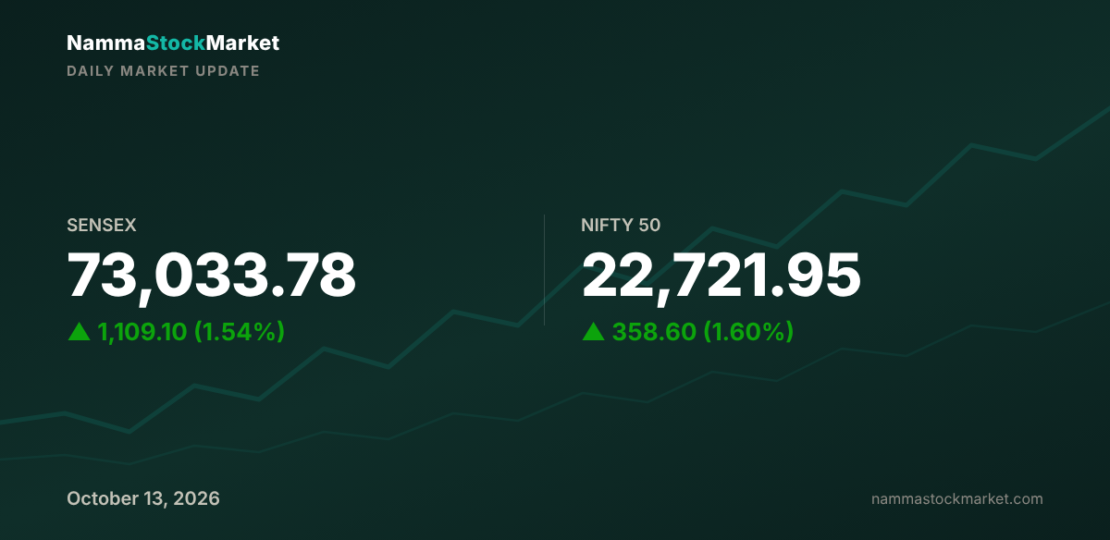
The Indian stock market had a cracking day today. The BSE Sensex jumped 1,109.10 points to close at 73,033.78, and the NSE Nifty 50 climbed 358.60 points to end at 22,721.95 — both up roughly 1.6%, their best single-day gain in weeks. If you were watching your portfolio turn red for the last few sessions, today was the day that made up for a lot of it. Two things drove this rally. First, IT stocks staged a massive comeback after HCL Technologies posted a much better-than-expected September quarter profit, and that set off buying across the whole technology pack. Second, Finance Minister Nirmala Sitharaman said the government is open to hearing industry views on capital gains tax (LTCG) and the Securities Transaction Tax (STT) ahead of the next Budget, and that comment alone sent the market into the last hour of trading on a high note.
For readers newer to the market, a quick note on names: the NSE (National Stock Exchange) is where the Nifty 50 trades, and the BSE (Bombay Stock Exchange) is where the Sensex trades. These are India’s two big stock exchanges, and the Sensex and Nifty are simply baskets of India’s top companies, used as a quick gauge of how the overall Indian stock market or Indian share market is doing on any given day.
Market At A Glance
| Index | Close | Points Change | % Change |
|---|---|---|---|
| BSE Sensex | 73,033.78 | ▲ 1,109.10 | ▲ 1.54% |
| NSE Nifty 50 | 22,721.95 | ▲ 358.60 | ▲ 1.60% |
| Bank Nifty | 55,481.05 | ▲ 563.05 | ▲ 1.03% |
| Nifty Midcap 100 | — | — | ▲ 1.06% |
| Nifty Smallcap 100 | — | — | ▲ 0.11% |
| India VIX | ~14.5 | — | ▼ 4.8% |
Note: Closing values for Nifty Midcap 100 and Nifty Smallcap 100 weren’t separately available at the time of writing, so only their percentage moves are shown. India VIX is shown as an early-session reading (around 14.5, down about 4.8% from Monday’s close of 15.25) since the exact closing print wasn’t out yet — but the direction was clearly down through the day, which fits with how confidently the market rallied.
Why The Market Moved
Today’s rally really had two engines. The first was earnings. HCL Technologies, one of India’s big IT services companies, reported a 21.2% jump in profit for the July-September quarter, way above what analysts were expecting. That’s a big deal because IT stocks have been beaten down for months on worries about slower spending by US and European clients and about AI disrupting the services business. When a bellwether like HCL Tech beats expectations this clearly, it tells the market that the worst fears may be overdone, and money rushed back into TCS, Infosys, Tech Mahindra, Wipro and the rest of the IT pack.
The second engine was the Finance Minister’s comments on LTCG (long-term capital gains tax, which you pay on profits from shares or mutual funds held over a year) and STT (the small tax deducted every time you buy or sell shares). She didn’t announce any change — she only said the government is willing to listen to industry feedback as it starts work on the next Budget. But that was enough for traders to start betting that taxes on equity investors could ease a bit down the line, and the Sensex added a big chunk of today’s gain in the final hour after her remarks came out.
There were headwinds too, and it’s worth knowing about them even on a day like this. September’s retail inflation came in at 5.54%, higher than expected and getting close to the RBI’s (Reserve Bank of India) upper comfort limit of 6%. Higher inflation makes it harder for the RBI to cut interest rates, which isn’t great news for borrowers or for rate-sensitive sectors. Crude oil also stayed above $100 a barrel through the session, and that matters a lot for India because we import most of our oil — a costlier oil import bill means more dollars flowing out, which puts pressure on the rupee and ultimately on inflation at home. None of that stopped today’s rally, but it’s the kind of thing that could cap how much further the market runs from here.
Which Sectors Held Up, And Which Didn’t
| Sector | % Change |
|---|---|
| Nifty IT | ▲ 5.22% |
| Nifty Realty | ▲ 2.46% |
| Nifty Consumer Durables | ▲ 1.56% |
| Nifty Financial Services | ▲ 1.46% |
| Nifty FMCG | ▲ 1.40% |
| Nifty Auto | ▲ 1.23% |
| Nifty Metal | ▲ 1.15% |
| Nifty Bank | ▲ 1.03% |
| Nifty Energy | ▲ 0.33% |
| Nifty Pharma | ▼ 0.01% |
IT was the clear star of the day, up over 5%, by far the best-performing sector. Realty (real estate stocks) also had a strong day, helped by hopes that easing bond yields could eventually bring down home loan rates. Consumer durables, financial services, FMCG (fast-moving consumer goods — the everyday products companies like Hindustan Unilever and ITC make), auto and metals all posted solid gains between 1% and 1.6%, showing the buying wasn’t limited to just one pocket of the market. Banking, tracked through Bank Nifty, added just over 1%, a reasonably good day though it lagged the broader rally a bit. Pharma was the only sector to end in the red, just barely, while energy stocks managed a small gain despite elevated crude prices. If you’re holding IT stocks in your demat account, today was clearly a very good day for your portfolio.
Today’s Top Movers
Top Gainers
| Stock | Close Price | % Change |
|---|---|---|
| HCL Technologies | ₹1,320.10 | ▲ 7.94% |
| Tata Consultancy Services | ₹2,269.30 | ▲ 6.79% |
| Shriram Finance | ₹986.20 | ▲ 6.11% |
| Tech Mahindra | ₹1,538.90 | ▲ 4.62% |
| Infosys | ₹1,061.15 | ▲ 4.03% |
HCL Technologies led the gainers’ list by a distance, up nearly 8% on the back of that strong earnings beat, with TCS and Shriram Finance not far behind. Tech Mahindra and Infosys rounded out the top five, both benefiting from the same wave of buying that lifted the whole IT sector today.
Top Losers
| Stock | Close Price | % Change |
|---|---|---|
| Kotak Mahindra Bank | ₹439.00 | ▼ 0.99% |
| Eternal | ₹320.45 | ▼ 0.79% |
| Max Healthcare Institute | ₹861.00 | ▼ 0.57% |
| Maruti Suzuki India | ₹11,259.00 | ▼ 0.49% |
| HDFC Life Insurance | ₹558.05 | ▼ 0.21% |
The losers’ list was a much shorter and shallower one today — nothing fell more than 1%, which tells you how broad-based the buying was. Kotak Mahindra Bank and Eternal (formerly Zomato) led the laggards, while Maruti Suzuki and HDFC Life saw only mild profit booking. On a day like this, a stock being “down” often just means it didn’t keep pace with the rally, not that there was any real selling pressure.
What FIIs And DIIs Were Doing
You’ll often see FII and DII numbers quoted in market reports, so here’s what they mean in simple terms. FII stands for Foreign Institutional Investor (sometimes also called FPI, or Foreign Portfolio Investor) — these are big global funds investing money into Indian shares from outside the country. DII stands for Domestic Institutional Investor — these are Indian mutual funds, insurance companies and similar big local investors. Watching whether FIIs and DIIs are net buyers or net sellers on a given day tells you a lot about where the “smart money” is leaning.
| Date | FII Net (₹ Crore) | DII Net (₹ Crore) |
|---|---|---|
| 6 October 2026 | ▼ 2,961.30 | ▲ 5,088.90 |
| 7 October 2026 | ▼ 6,121.40 | ▲ 4,596.60 |
| 8 October 2026 | ▼ 12,943.60 | ▲ 10,703.10 |
| 9 October 2026 | ▼ 3,568.90 | ▲ 4,743.30 |
| 12 October 2026 | ▼ 1,708.50 | ▲ 3,045.00 |
Today’s (13 October) FII/DII cash-segment figures weren’t out at the time of writing — these numbers usually get published after market hours, so we’ve shown you the last five trading days instead, with dates clearly marked, so you can see the pattern. And the pattern has been remarkably consistent: FIIs have been net sellers every single day shown here, part of what’s now been a 12-session selling streak for foreign investors, with October outflows crossing roughly $4.9 billion. But DIIs — your mutual fund SIPs and insurance money, basically — have been net buyers on every one of those same days, quietly absorbing the foreign selling and cushioning the market from bigger falls. This is a big reason why, despite all the FII selling you keep hearing about, the Indian market hasn’t cracked — domestic money, a lot of it coming in through SIP (systematic investment plan) contributions every month, has been steady support underneath.
Oil, The Rupee, And Global Cues
Brent crude (the international benchmark for oil, always quoted in US dollars per barrel since it’s a globally traded commodity) eased about 1.1% today to around $105.47 a barrel, cooling off a bit after a sharp rally in the previous session that was driven by fears of supply disruptions tied to attacks on Saudi Arabia’s oil infrastructure. Even with today’s dip, crude remains well above $100, and that keeps a key worry alive for India: we import close to 85% of our oil needs, so every dollar increase in crude adds to our oil import bill, which in turn weakens the rupee and adds to inflation at the petrol pump and across the economy. That’s why you’ll keep hearing Indian market commentators talk about crude oil even though it has nothing to do with Indian companies directly — it feeds straight into the cost of doing business here and into what you pay for fuel.
The rupee had a strong day, gaining around 0.58% against the US dollar to trade near ₹95.20, its best level in about a month. The RBI stepped in with a fresh set of measures to support the currency — including a special dollar-buying window for three state-run oil marketing companies and tighter rules on non-deliverable forward (NDF) currency contracts, which are often used to speculate on where the rupee is headed. Traders believe state-run banks were also selling dollars on the RBI’s behalf to help the rupee along. This happened even as FIIs kept pulling money out and while a hawkish tone from the US Federal Reserve kept the dollar generally strong globally — so the RBI’s direct intervention did a lot of the heavy lifting today. Globally, cues were mixed: Asian markets, including South Korea’s KOSPI, fell sharply on weakness in US technology shares, but that didn’t stop Indian IT stocks from having their best day in a long while, which shows just how much today’s rally was being driven by India-specific news rather than global sentiment.
What To Watch Tomorrow
A few things are worth keeping an eye on as we head into the next session. September retail inflation at 5.54% is uncomfortably close to the RBI’s 6% tolerance ceiling, so any follow-up commentary from RBI officials on the MPC’s (Monetary Policy Committee’s) rate stance could move bond yields and, in turn, rate-sensitive sectors like banking, auto and realty. The US CPI inflation report due this week is another one to track — a hot reading there could revive expectations of the Fed staying hawkish for longer, which tends to pressure emerging-market currencies including the rupee. On the technical side, market watchers are flagging 22,830–22,850 as the next resistance zone for the Nifty; a decisive move above that could open the door toward 23,000, while 22,550–22,580 is being seen as near-term support. IT looks like the sector to watch after today’s breakout — whether this is the start of a real trend reversal or just a one-day bounce on a single good earnings print will likely become clearer as more IT majors report their numbers this month. Energy and oil-sensitive names remain the ones most exposed if crude prices pick back up. As always, none of this is a buy or sell call — just the things that are likely to set the tone for trading tomorrow.
RELATED POSTS
View all

Sensex Jumps 333 Points, Nifty Reclaims 23,200 As UPI Fee Move Lifts Banks; IT Stocks Buck The Trend
September 16, 2026 | by NammaStockMarket
Sensex Gains 299 Points, Nifty Ends Above 23,400 As Crude Oil Drops Below $100; Metal Stocks Jump 2.4%, IT Slips
September 23, 2026 | by NammaStockMarket
Sensex Sinks 571 Points, Nifty Slips Below 22,450 As Crude Oil Tops $100 And US Bond Yields Spook D-Street
October 1, 2026 | by NammaStockMarket