

Stock Market Today, 4 November 2026: GIFT Nifty, Sensex and Nifty Pre-Market Cues, FII DII Data and Stocks in News
November 4, 2026 | by NammaStockMarket
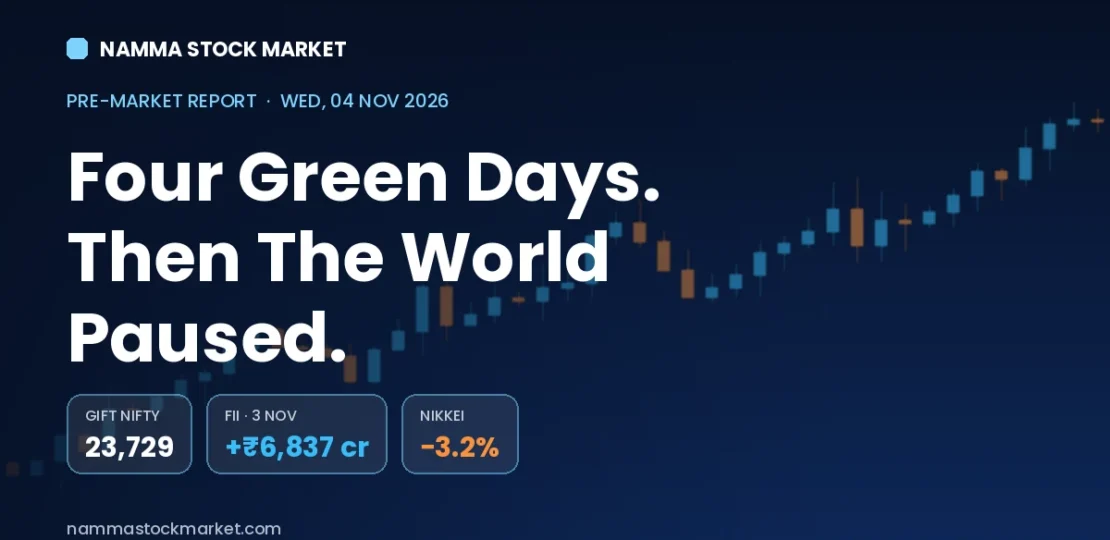
NSE pre-market report · Data as of 8:15 AM IST · NSE and BSE open at 9:15 AM IST
Good morning. Let us get you ready for the share market today over a quick cup of chai. Yesterday was a party on Dalal Street — the fourth straight day of gains, with the Sensex adding over 1,200 points. But this morning the mood is a little more careful. GIFT Nifty today is trading slightly lower, Japan’s Nikkei has fallen sharply, and the world is waiting for US mid-term election results.
Below you will find where Nifty 50 and Sensex closed on Tuesday, what the overnight global cues look like, the latest FII DII data, the stocks in the news because of their Q2 results, and where things stand on F&O expiry this week. One thing before we start: we do not make predictions or give buy-sell calls here. This is news, data and plain-English explanation only.
1. Global Market Cues Today: US Markets, Asian Markets, Crude Oil and Rupee
US markets closed in a split mood on Tuesday, 3 November. The Dow slipped while technology shares pulled the Nasdaq higher. Apple fell around 2% after its iPad sales came in below what analysts expected, but chip and AI-linked names such as Nvidia, Micron, AMD and Oracle rose between roughly 2% and 6%.
| Index | Close | Change |
|---|---|---|
| Dow Jones Industrial Average | 51,786.72 | − 0.38% |
| S&P 500 | 7,568.92 | + 0.36% |
| Nasdaq Composite | 25,372.01 | + 0.83% |
| US 10-year bond yield | 4.96% | — |
| Dollar Index (DXY) | 101.448 | − 0.41% |
The big event is the US mid-term elections, which were held on Tuesday. Results were still being counted at the time of writing, and US index futures were softer as investors waited. When a major political result is pending, global money tends to sit on its hands for a day or two — that is the mood this morning.
Asian markets are mostly down. Japan’s Nikkei 225 is the standout faller.
| Asian Index | Change (as of ~8:13 AM IST) |
|---|---|
| Nikkei 225 (Japan) | − 3.20% |
| KOSPI (South Korea) | − 1.44% |
| Straits Times / FTSE Singapore | − 1.12% |
| Hang Seng (Hong Kong) | − 0.34% |
| Shanghai Composite (China) | − 0.24% |
Two more things from Asia worth knowing. China’s central bank, the PBOC, has raised the foreign-currency reserve requirement for banks to 6% from 4%, effective 15 November — a step that usually signals discomfort with currency moves. And readings on Hong Kong and Korea varied quite a bit between 7:00 AM and 8:15 AM IST, so treat the exact numbers above as a snapshot, not a settled close.
Now commodities and our currency.
| Commodity / Currency | Level | Change |
|---|---|---|
| Brent crude (ICE January futures) | $103.20 /bbl | − 1.07% |
| WTI crude | $96.85 /bbl | − 0.92% |
| MCX Gold (December futures) | ₹1,38,398 /10 g | − 1.28% |
| MCX Silver (December futures) | ₹1,77,085 /kg | − 3.64% |
| Rupee (USD/INR, 3 Nov close) | ₹94.75 | + 15 paise |
Crude is the story to keep half an eye on. Brent fell about 7.6% on Monday on hopes of a settlement in West Asia, then bounced back after reports of fresh US strikes on Iran’s Qeshm Island, and is easing again today. Readings this morning ranged from about $103 to $107 across different sources and contract months, so the direction is clearer than the exact number: crude is off its highs but still above $100, which matters for India because we import most of our oil.
The rupee closed at ₹94.75 against the US dollar on Tuesday, its third straight day of gains, from ₹94.90 earlier. It opened at 94.68 and touched 94.61 during the day before giving back some of that. Foreign inflows into Indian shares helped; the crude rebound and the US election wait held it back. In early trade today it was around ₹94.73.
2. GIFT Nifty Today (SGX Nifty): The First Pre-Market Indicator
GIFT Nifty is the old SGX Nifty, now traded at NSE International Exchange in GIFT City, Gujarat. Because it trades for nearly the whole day, it is the first clue we get about how Nifty may open at 9:15 AM. It is an indicator, not a promise — many mornings the market opens one way and turns around within minutes.
| Item | Value |
|---|---|
| GIFT Nifty (November contract) | 23,728.50 |
| Change | − 31.50 pts (− 0.13%) |
| Gap vs Nifty’s Tuesday close | about − 82 pts |
| Nifty 50 previous close | 23,810.85 |
| Reading time | ~8:15 AM IST |
So GIFT Nifty is pointing to a soft, slightly lower start after four strong sessions. Readings at 7:00 AM, 7:45 AM and 8:15 AM all sat in the 23,725–23,732 band, which is a consistent picture. What it signals is a pause in the rally, not a reversal — and the first 15 minutes of trade will tell us far more than any pre-market number.
3. Nifty 50 and BSE Sensex Today: Previous Close
Tuesday was a strong, broad-based session. The Sensex today starts from 76,917.85 after adding 1,225.07 points, and the Nifty from 23,810.85. Both closed at roughly their highest levels in nearly two months. Market breadth was healthy too — on the BSE, 2,362 shares advanced against 1,862 that fell, with 156 unchanged.
| Index | Close (3 Nov 2026) | Change | Change % |
|---|---|---|---|
| Nifty 50 | 23,810.85 | + 370.05 | + 1.58% |
| BSE Sensex | 76,917.85 | + 1,225.07 | + 1.62% |
| Nifty Bank | — | — | + 0.80% |
| Nifty Midcap 100 | — | — | + 1.06% |
| Nifty Smallcap 100 | — | — | + 0.31% |
| Move from 29 Oct low | — | about + 1,300 pts | — |
Nifty traded between 23,482.80 and 23,810.85 and finished at the top of that range — closing at the day’s high is usually read as a sign of steady buying right into the bell. Over four sessions the index has travelled roughly 1,300 points from its 29 October low, which is a big move in a short time.
Sector by sector, consumption and rate-sensitive names led while PSU banks and energy lagged.
| Sector | Change (3 Nov) |
|---|---|
| Nifty FMCG | + 2.50% |
| Nifty Realty | + 2.10% |
| Nifty Private Bank | + 1.98% |
| Nifty Auto | + 1.70% |
| Nifty Bank | + 0.80% |
| Nifty Media | + 0.50% |
| Nifty Energy | − 0.40% |
| Nifty PSU Bank | − 1.40% |
And here are the names that moved the most.
| Stock | Change (3 Nov) |
|---|---|
| BSE Ltd | + 5.03% |
| Nestle India | + 4.47% |
| Tata Consumer Products | + 4.29% |
| Asian Paints | + 3.99% |
| Bharti Airtel | + 3.77% |
| Adani Enterprises | − 0.84% |
| Infosys | − 1.11% |
| ONGC | − 1.13% |
| State Bank of India | − 1.70% |
| Power Grid Corporation | − 3.04% |
Nifty Support and Resistance Levels for Today
A quick word on what these are. Support is a level where buying has tended to show up; resistance is where selling has tended to appear. The levels below are drawn from where option traders have built up the largest positions — in other words, the levels the market is watching. They are for reference, not forecasts, and nobody can tell you where an index will actually go.
| Level / Measure | Value | What it means |
|---|---|---|
| OI-based resistance | 23,850 | Strike with the heaviest call open interest |
| Max pain | 23,700 | Strike where most option buyers would lose |
| OI-based support | 22,500 | Strike the chain shows as support |
| Previous close | 23,810.85 | Tuesday’s Nifty 50 close |
| India VIX | 15.72 | Up 1.42% |
India VIX at 15.72 is the market’s “fear gauge” — it measures how much movement traders expect over the next 30 days. A reading in the mid-teens is fairly calm. Note that Nifty’s close of 23,810.85 sits just below the 23,850 call-heavy strike, and the round 24,000 mark is the next level people are talking about.
4. FII DII Data Today: Tuesday, 3 November 2026 (₹ Crore)
This is the table many of you check first. FIIs (Foreign Institutional Investors) are overseas funds; DIIs (Domestic Institutional Investors) are Indian mutual funds, insurers and pension funds. On Tuesday foreign money came in strongly while domestic institutions took some money off the table.
| Category | Gross Buy | Gross Sell | Net |
|---|---|---|---|
| FII / FPI (cash) | 20,970.50 | 14,133.70 | + 6,836.80 |
| DII (cash) | 16,723.90 | 20,402.80 | − 3,678.80 |
An FII net buy of ₹6,837 crore in a single day is a big number, and it was the second straight day of foreign buying — FIIs had also bought ₹3,114.70 crore on Monday, 2 November. Here is how the month has started.
| Period | FII Net | DII Net |
|---|---|---|
| 3 Nov 2026 | + 6,836.80 | − 3,678.80 |
| 2 Nov 2026 | + 3,114.70 | − 392.20 |
| November so far (2–3 Nov) | + 9,951.50 | − 4,071.00 |
Why does this matter? FIIs move large sums, so sustained foreign buying often supports the market, while DII selling can simply mean domestic funds are booking profits after a sharp run-up. These are provisional exchange figures for the cash segment and get revised slightly later.
5. Stocks in News Today: Stocks in Focus on 4 November 2026
These companies are in the news this morning for factual reasons — mostly Q2 FY27 results that came out after market hours. This is an observation of news, not a recommendation, and there are no targets or calls here.
| Company | Why It’s in the News |
|---|---|
| MCX | Q2 consolidated net profit ₹454.57 crore, up 130% YoY; revenue up 114%; EBITDA up 151% |
| NSE | Consolidated Q2 FY27 profit of ₹2,578 crore, up 23% YoY |
| BSE Ltd | Board scheduled to consider September-quarter results today; stock rose 5.03% on Tuesday |
| ITC | Q2 net profit fell about 18%; stock still ended higher on Tuesday |
| Bata India | Q2 net profit about ₹18 crore, up 30.4%; revenue ₹861.78 crore, up 7.54% |
| Happiest Minds | Q2 net profit ₹62 crore, up 15.12%; interim dividend of ₹3.05 per share; exceptional charge linked to the proposed ITC Infotech merger |
| Minda Corporation | Q2 net profit ₹143 crore, up 68.2%; revenue ₹2,189 crore, up 42.6% |
| Emcure Pharmaceuticals | Q2 consolidated net profit ₹325.06 crore; revenue ₹2,820.47 crore |
| Nexus Select Trust | Q2 net operating income ₹504 crore, up 8%; distribution of ₹359 crore |
| Utkarsh Small Finance Bank | Q2 net loss of ₹70 crore, a sixth straight quarterly loss; gross NPA at 5.96% |
| Marico | Rose about 10% on Tuesday after Q2 earnings, helped by lower copra costs |
| Woodstock Broking, Marfatia Stock Broking | SEBI imposed penalties totalling ₹40 lakh on four entities in a front-running case covering trades from April 2021 to March 2022 |
6. Key Events Today: A Heavy Q2 Results Day and US Election Results
Today is one of the busiest earnings days of this season, with around 80 companies scheduled to report Q2 FY27 numbers. The larger names on the list include Apollo Hospitals, Dabur India, Cummins India, Aurobindo Pharma, Exide Industries, Biocon, Apollo Tyres, Zydus Lifesciences, Power Finance Corporation, PI Industries, NHPC, Torrent Power, Dr Lal PathLabs, Nykaa (FSN E-Commerce), Physicswallah, JM Financial, Kansai Nerolac Paints, Balkrishna Industries, HUDCO and BSE Ltd.
On the primary market side, the Vedant Poly Fabs IPO is on its final day of subscription, looking to raise ₹56.68 crore.
Globally, the counting of US mid-term election results is the main event. Markets everywhere will react to the outcome, so expect some volatility through the day. Also watch crude oil, given the continuing West Asia tension around Iran and the Strait of Hormuz.
7. F&O Today: Nifty Expiry, Open Interest and F&O Ban List
Let us decode the jargon in this section, because it trips up a lot of new traders.
Open interest (OI) is the number of futures and options contracts still open and not yet settled. Rising OI means fresh money is coming into that contract. PCR, or put-call ratio, divides put open interest by call open interest; a high PCR means many more puts than calls are open. Max pain is the strike price at which the largest number of option buyers would lose money at expiry — it often acts like a magnet near expiry. MWPL is the market-wide position limit: the maximum open position allowed across the market in a single stock’s derivatives.
| Measure | Value (as of 3 Nov close) |
|---|---|
| Nifty PCR (put-call ratio) | 1.92 |
| Max pain strike | 23,700 |
| Highest call OI strike | 23,850 |
| Support strike per chain | 22,500 |
| Nifty lot size | 65 |
| India VIX | 15.72 |
A PCR of 1.92 is on the high side, which simply tells you a lot of put writing has happened at lower strikes. Do remember these are closing-session figures; the chain will look different once trading begins.
Now, expiry. This week has a twist worth noting on your calendar.
| Expiry | Day | Note |
|---|---|---|
| Sensex weekly | Thursday, 5 November 2026 | Tomorrow |
| Nifty weekly | Tuesday falls on 10 November | 10 Nov is a Diwali-Balipratipada trading holiday |
| Nifty monthly F&O | Monday, 23 November 2026 | Current near-month contract carries this expiry date |
Nifty weekly contracts expire on Tuesdays and Sensex weeklies on Thursdays. Next Tuesday, 10 November, is Diwali-Balipratipada and the exchanges are shut. When an expiry day falls on a holiday, NSE normally moves it to the previous trading day — and it confirms every such change by circular, so please check the NSE circular rather than assuming. The same applies to the monthly expiry: the last Tuesday of November is the 24th, which is Guru Nanak Jayanti, and the near-month Nifty futures contract already shows 23 November 2026 as its expiry date.
F&O ban list: the latest confirmed NSE ban list is for the 3 November trade date, and it had two stocks — Kaynes Technology India and Steel Authority of India (SAIL). We could not confirm today’s list at the time of writing, so please check the NSE website for the 4 November ban file before trading. Stocks approaching the threshold on Tuesday included Bandhan Bank, Manappuram Finance, LIC Housing Finance, Ambuja Cements and Inox Wind. A stock in the ban period can only be traded to reduce an existing position, not to open a new one, and it exits the ban once utilisation falls back below 80%.
FAQs: Share Market Today (4 November 2026)
What is GIFT Nifty today?
GIFT Nifty (November contract) was at 23,728.50 around 8:15 AM IST, down 31.50 points or 0.13%. That is roughly 82 points below Nifty’s Tuesday close of 23,810.85, pointing to a soft start.
Where did Nifty 50 and Sensex close on 3 November 2026?
Nifty 50 closed at 23,810.85, up 370.05 points or 1.58%. The BSE Sensex closed at 76,917.85, up 1,225.07 points or 1.62%. It was the fourth straight session of gains for both.
What are the Nifty support and resistance levels today?
Based on option open interest at Tuesday’s close, the heaviest call OI sits at the 23,850 strike, max pain is at 23,700, and the chain shows support at 22,500. These are levels traders watch, shared for reference and not as forecasts.
What is the FII DII data for 3 November 2026?
FIIs were net buyers of ₹6,836.80 crore in the cash segment (bought ₹20,970.50 crore, sold ₹14,133.70 crore). DIIs were net sellers of ₹3,678.80 crore (bought ₹16,723.90 crore, sold ₹20,402.80 crore). These are provisional figures.
When is the Nifty expiry this week?
Nifty weekly options expire on Tuesdays, and the next Tuesday is 10 November, which is a Diwali-Balipratipada trading holiday. NSE usually shifts an expiry that lands on a holiday to the previous trading day and confirms it by circular, so check the NSE circular for the exact date. The Sensex weekly expiry is Thursday, 5 November, and the near-month Nifty futures contract shows 23 November 2026 as its expiry.
Which stocks are in the F&O ban list today?
The last confirmed NSE ban list, for the 3 November trade date, contained Kaynes Technology India and Steel Authority of India (SAIL). Today’s list could not be confirmed before publishing — check the NSE F&O ban file for 4 November.
Is there a Nifty prediction today?
No — we do not make predictions, and you should be cautious of anyone who does. What we can give you is the data: GIFT Nifty is pointing to a slightly lower open, Asian markets are weak with the Nikkei down over 3%, FIIs bought ₹6,837 crore on Tuesday, crude is easing but still above $100, and US election results are being counted. How you read that is your call, ideally with a SEBI-registered advisor.
Data sources: NSE and BSE closing data via Kotak Neo and HDFC Sky; GIFT Nifty and option chain data via NiftyTrader, Business Standard and DSIJ; FII/DII provisional figures via 5paisa and Trendlyne; global market data via ABC News, CNBC-TV18 and Upstox; rupee data via Business Standard; F&O ban list via Gale and 5paisa. Figures are as reported by these sources at approximately 8:15 AM IST on 4 November 2026 and are provisional. Where sources differed, the discrepancy has been noted in the text. Market data changes continuously — please verify on the NSE and BSE websites before acting on anything.
This report is for informational and educational purposes only and does not constitute investment advice. Please consult a SEBI-registered investment advisor before making any trading or investment decisions.
RELATED POSTS
View all

Stock Market Today, 27 October 2026: GIFT Nifty, Sensex and Nifty Pre-Market Cues, FII DII Data and Stocks to Watch
October 27, 2026 | by NammaStockMarket
Stock Market Today, 5 October 2026: GIFT Nifty Hints at a Gap-Up, Nifty and Sensex Pre-Market Cues, FII DII Data and Stocks in News
October 5, 2026 | by NammaStockMarket
Stock Market Today, 3 November 2026: GIFT Nifty, Sensex and Nifty Pre-Market Cues, FII DII Data and Stocks to Watch
November 3, 2026 | by NammaStockMarket